Perspectives
Where Physical Cash Has Its Limits
 Marc Werner
Loading Social Income...
Loading Social Income...
© 2026 Social Income · Registered Non-Profit in Switzerland
Platform partner

© 2026 Social Income · Registered Non-Profit in Switzerland
Loading Social Income...
Marc WernerWhen Aurélie and I visited Monrovia, getting the right kind of cash was surprisingly cumbersome. We had to either hunt down a dedicated forex office or make our way to the one ATM that reliably worked with our cards. During the rainy season—the tropical kind—nobody particularly wants to make that trek.
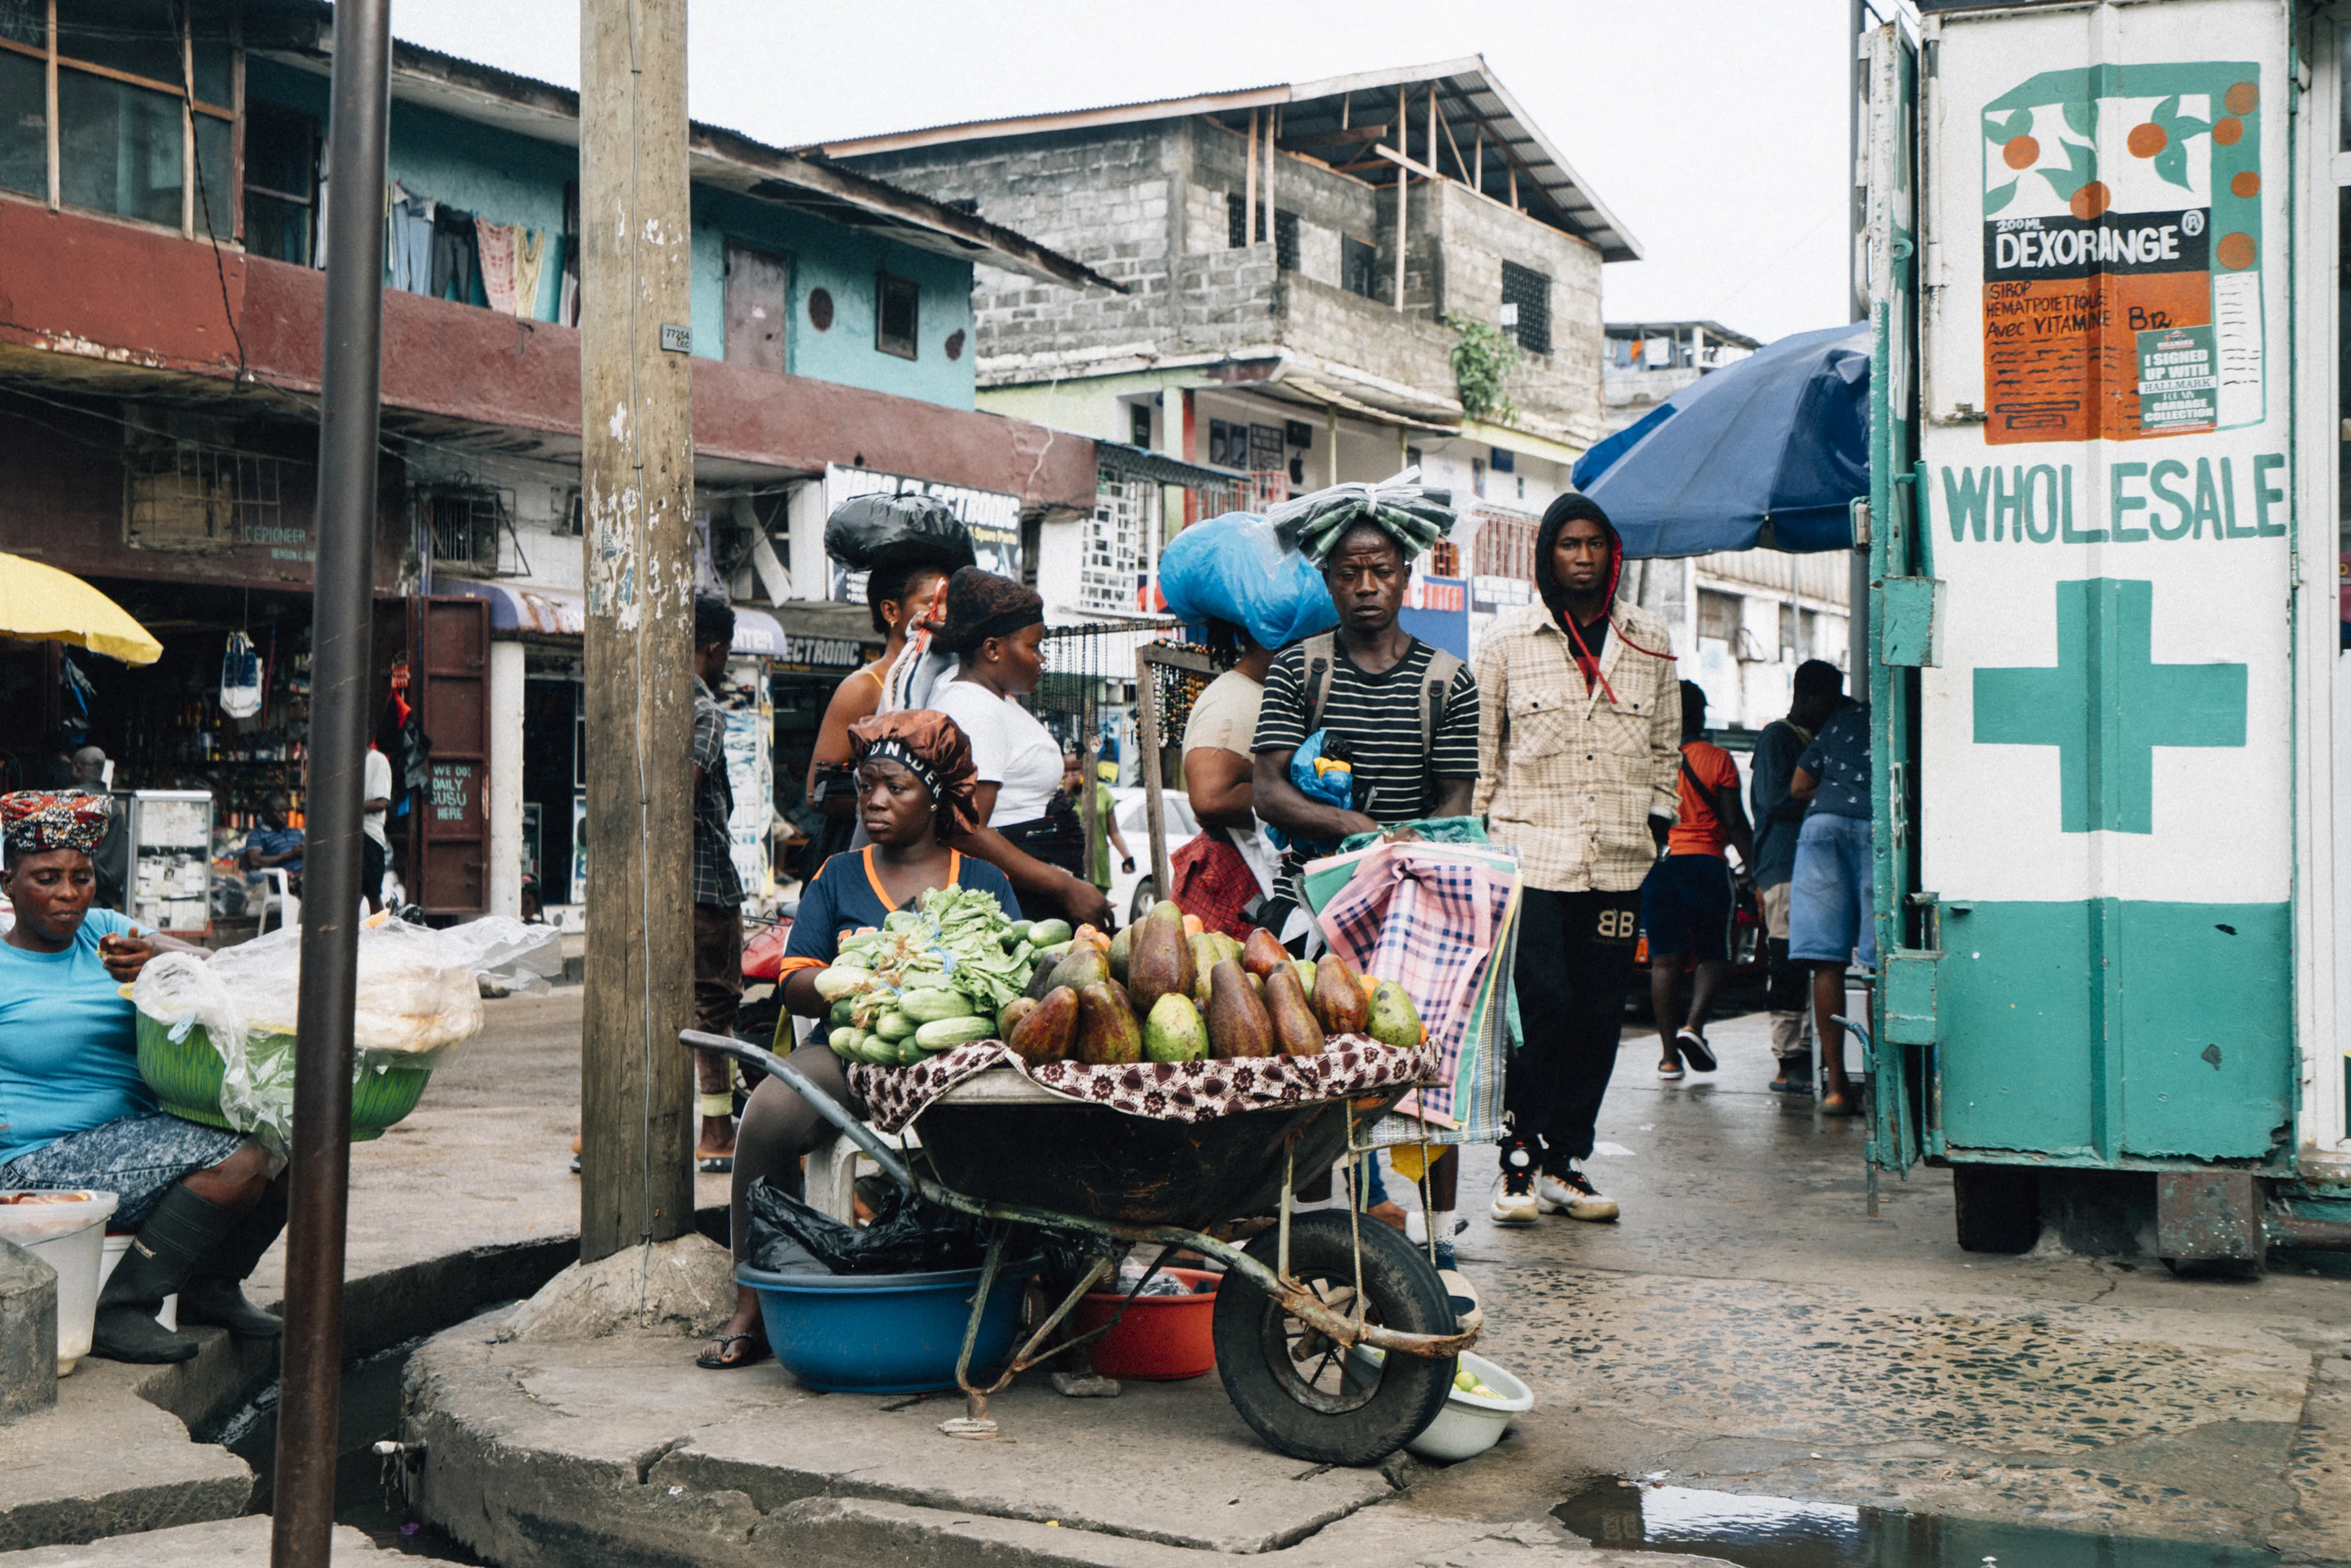
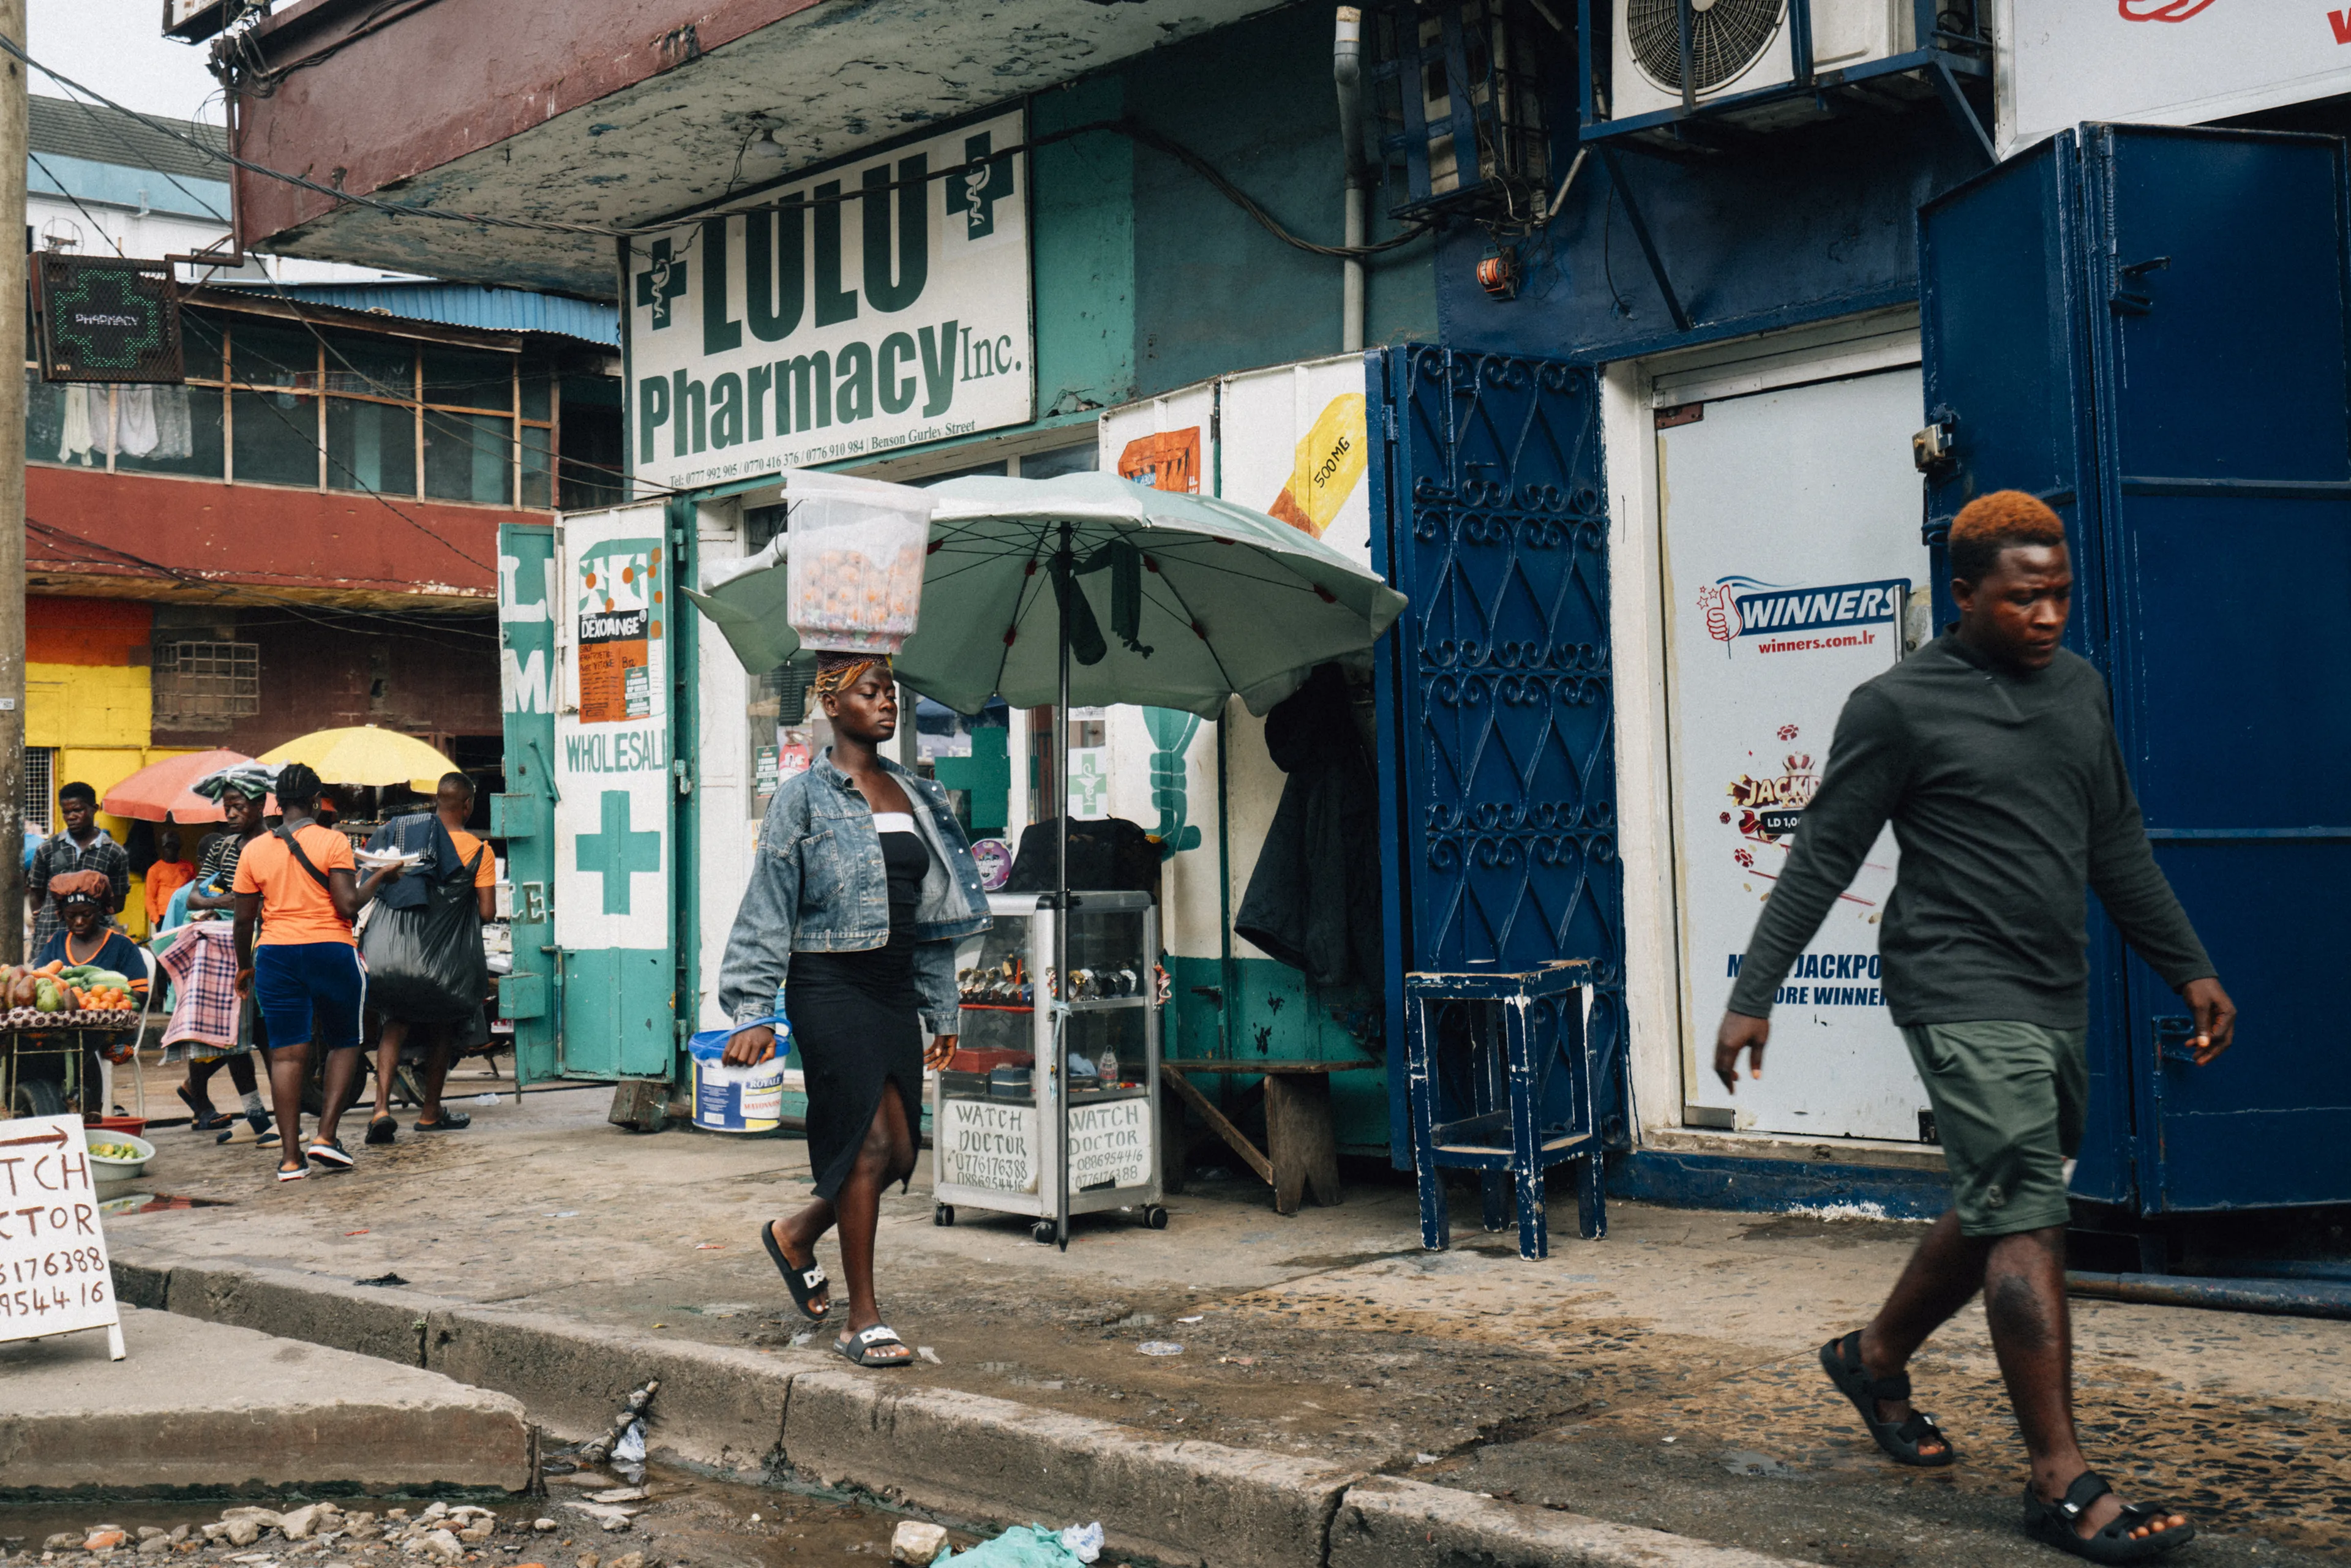
On our walk to that single viable ATM (a fun walk, I must admit), we must have passed at least ten mobile money booths. Having a mobile money wallet would have spared us the need to buy an umbrella. But in places like Liberia, mobile money goes far deeper than convenience. It is what makes an agency focused of giving possible.
So here's a thought experiment: What would Social Income look like in a world without mobile money? How would we get money to the people we support?
Let's go step by step.
Let's assume a world with banks and wire transfers. People can donate to a Social Income bank account, and we can wire that money to a bank account in a place like Liberia. Great, we now have the money where it needs to be.
Almost.
We now have the money sitting in a Liberian bank account. So why not simply transfer it to recipients' bank accounts? Because doing so would exclude many of the people we want to reach.
According to Global Findex 2025 microdata for Liberia, only 13.9% of adults have an account at a financial institution. Bank transfers alone would therefore drastically shrink our pool of eligible recipients.
So what about cash?
Paying recipients in physical cash would mean stacking up bills and coins and turning our country office into something looking like Scrooge McDuck's money bin. That's not just a safety risk. It would also take far more effort to transport, distribute, track, and account for the money.
And then there is the biggest problem: how does the cash actually reach people? Someone has to bring it to you, which creates costs, logistical challenges, and opportunities for leakage. Or you have to go and get it yourself, which creates costs, risks, and a considerable burden for the recipient.
Neither option is free. Neither is particularly safe. If cash isn't the answer, what is?
Almost half of Liberia's adult population—47.5%—uses a mobile money account, according to Global Findex 2025 data. That makes mobile money 3.4 times more prevalent than formal bank accounts. This is where the value of mobile money really becomes clear.
Money can be transferred almost instantly. It is protected by a PIN on your phone. You can use it directly to pay bills or buy things at the market. And if you want physical cash, you can still withdraw it. You can also send the money onwards to friends and family, something our recipients frequently do.
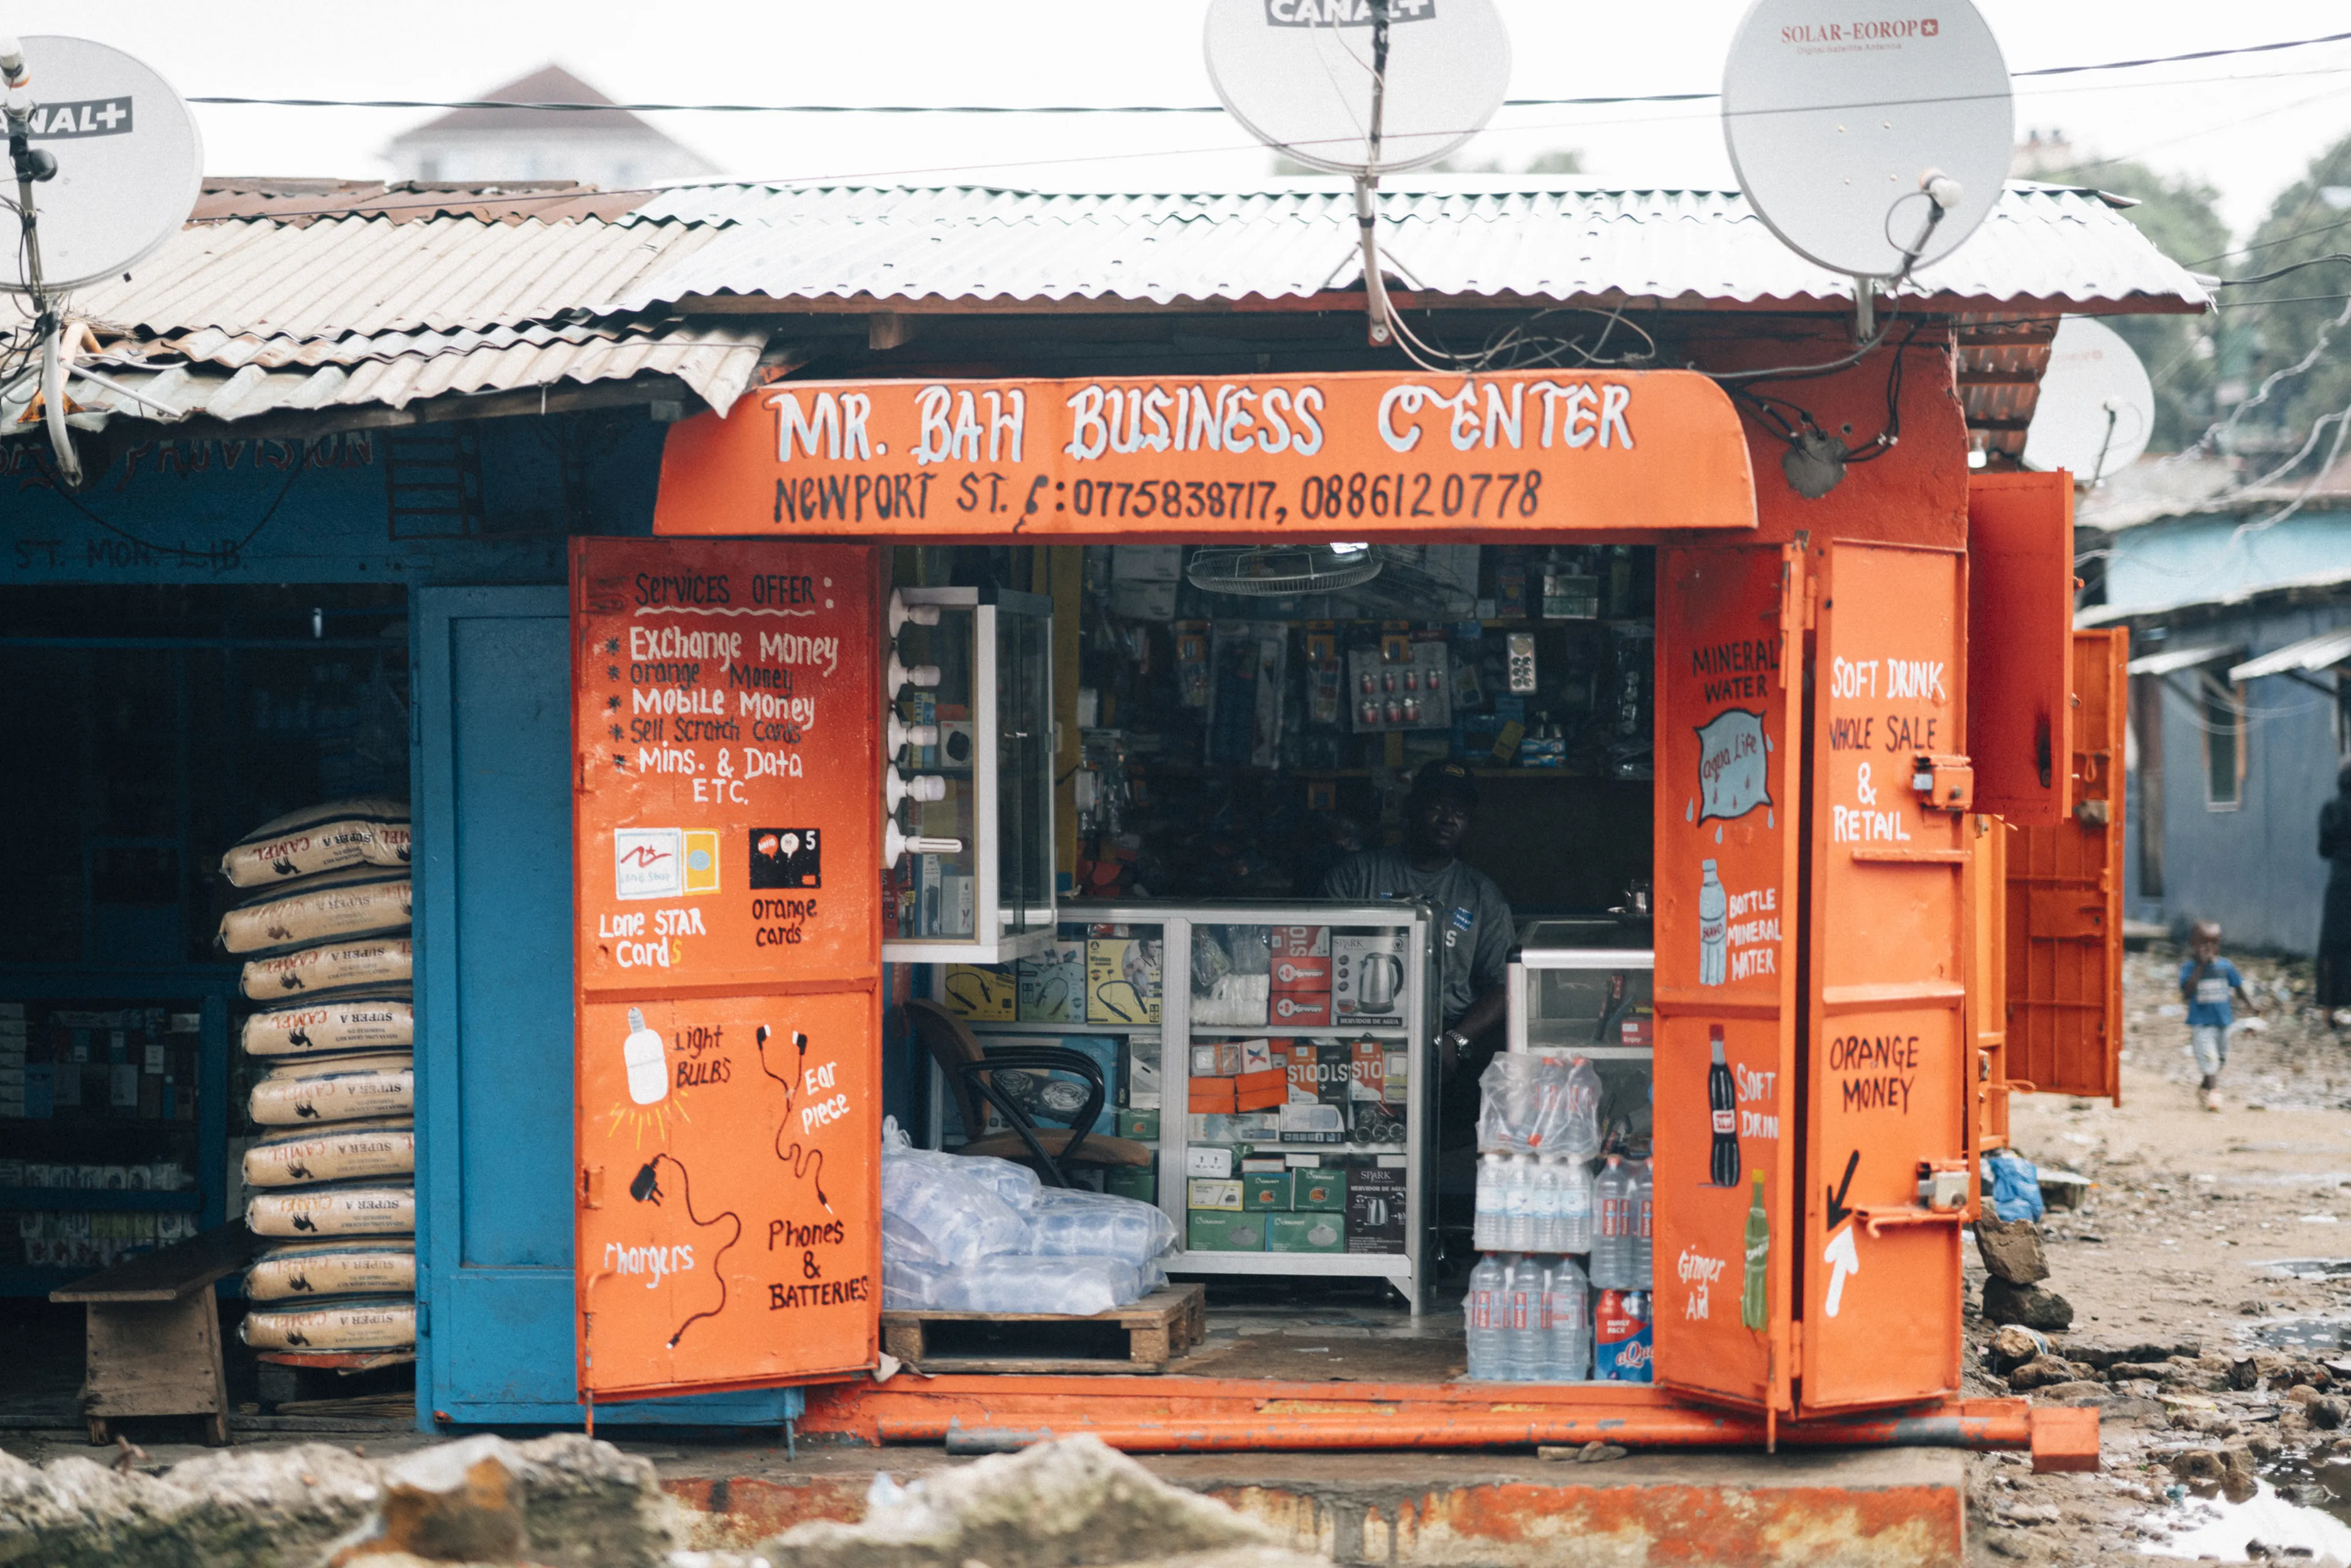
In other words, mobile money doesn't just solve the problem of getting money from A to B. It also gives recipients control over what happens after the money arrives.
Social Income is built around the idea that people experiencing poverty know best how to spend their money. We want to give them the means to make that decision themselves. Mobile money is the infrastructure that makes this possible at scale.
Of course, mobile money isn't universal yet.
At times, we've worked with our local partner organizations to help people buy their own phone so they can use mobile money too. But there are limits.
Where people cannot access a mobile network, don't have a phone, or otherwise cannot use mobile money, we can't pretend the infrastructure doesn't matter. There are places where Social Income cannot operate—at least not yet.
What about mobile money's shortcomings? Coverage can be patchy. Networks go down. Providers change. Cash-out points aren't equally accessible everywhere. These are real limitations, and we shouldn't gloss over them. But the relevant question isn't whether mobile money is perfect.
The relevant question is: what is the best available way to get unconditional cash into the hands of people who need it?
Against the alternatives, mobile money has a compelling advantage:
Cash is tangible, but expensive and cumbersome to move safely.
Bank accounts are efficient, but too few people have them and transfers are costly at scale.
In-kind aid can be useful in specific circumstances, but it asks someone else to decide what a person needs.
Mobile money combines the reach of cash with much of the efficiency of digital payments all the while while preserving something even more important: choice.
Mobile money is what turns a transfer into agency. The goal of Social Income isn't simply to move money from donors to recipients. The goal is to give people the freedom to decide what to do with that money.
So, if we return to our thought experiment—what would Social Income look like without mobile money?—the answer is straightforward: it would be harder to reach people, more expensive to operate, less safe, and ultimately less empowering.
Mobile money doesn't just make our work easier. It makes our model possible.
This article grew out of the 2026 Writathon in Bern.
Marc Werner